
You pay ₹40 for chai on PhonePe, ₹380 on Swiggy through Google Pay, ₹1,200 at the petrol pump by scanning a QR. By the 20th, the salary that landed on the 1st is half gone and you can’t say where. Writing every payment in a notebook lasts about four days.
Here is the short answer. You do not need to type anything to track UPI spending, because your bank already records every payment and sends you an SMS for it. Automatic tracking simply means collecting those messages into one list, with a category on each. You can do that with an app that reads bank SMS on your phone, or by hand once a week in about ten minutes.
This guide covers both, along with the few gaps where automatic tracking misses money and how to plug them.
Why UPI is easier to track than it looks
Each UPI app has its own history screen, so it feels as if your spending is scattered across three or four apps. But every UPI payment, whichever app you use, moves money out of a bank account. That bank is the one record that sees all of it.
RBI rules ask banks to get customers registered for SMS alerts on electronic banking transactions, and to send those alerts. So a typical UPI debit gives you a message with the amount, the last digits of your account, the date, the payee name or UPI ID, and a reference number. That message is the raw material for automatic tracking.
Compare that with the UPI apps themselves. Google Pay’s own help page says its history only covers payments made through Google Pay, not all your UPI or bank transactions. PhonePe and Paytm work the same way: each shows only its own payments. The bank SMS is the only place where they all meet.
Method 1: Let an app read your bank SMS
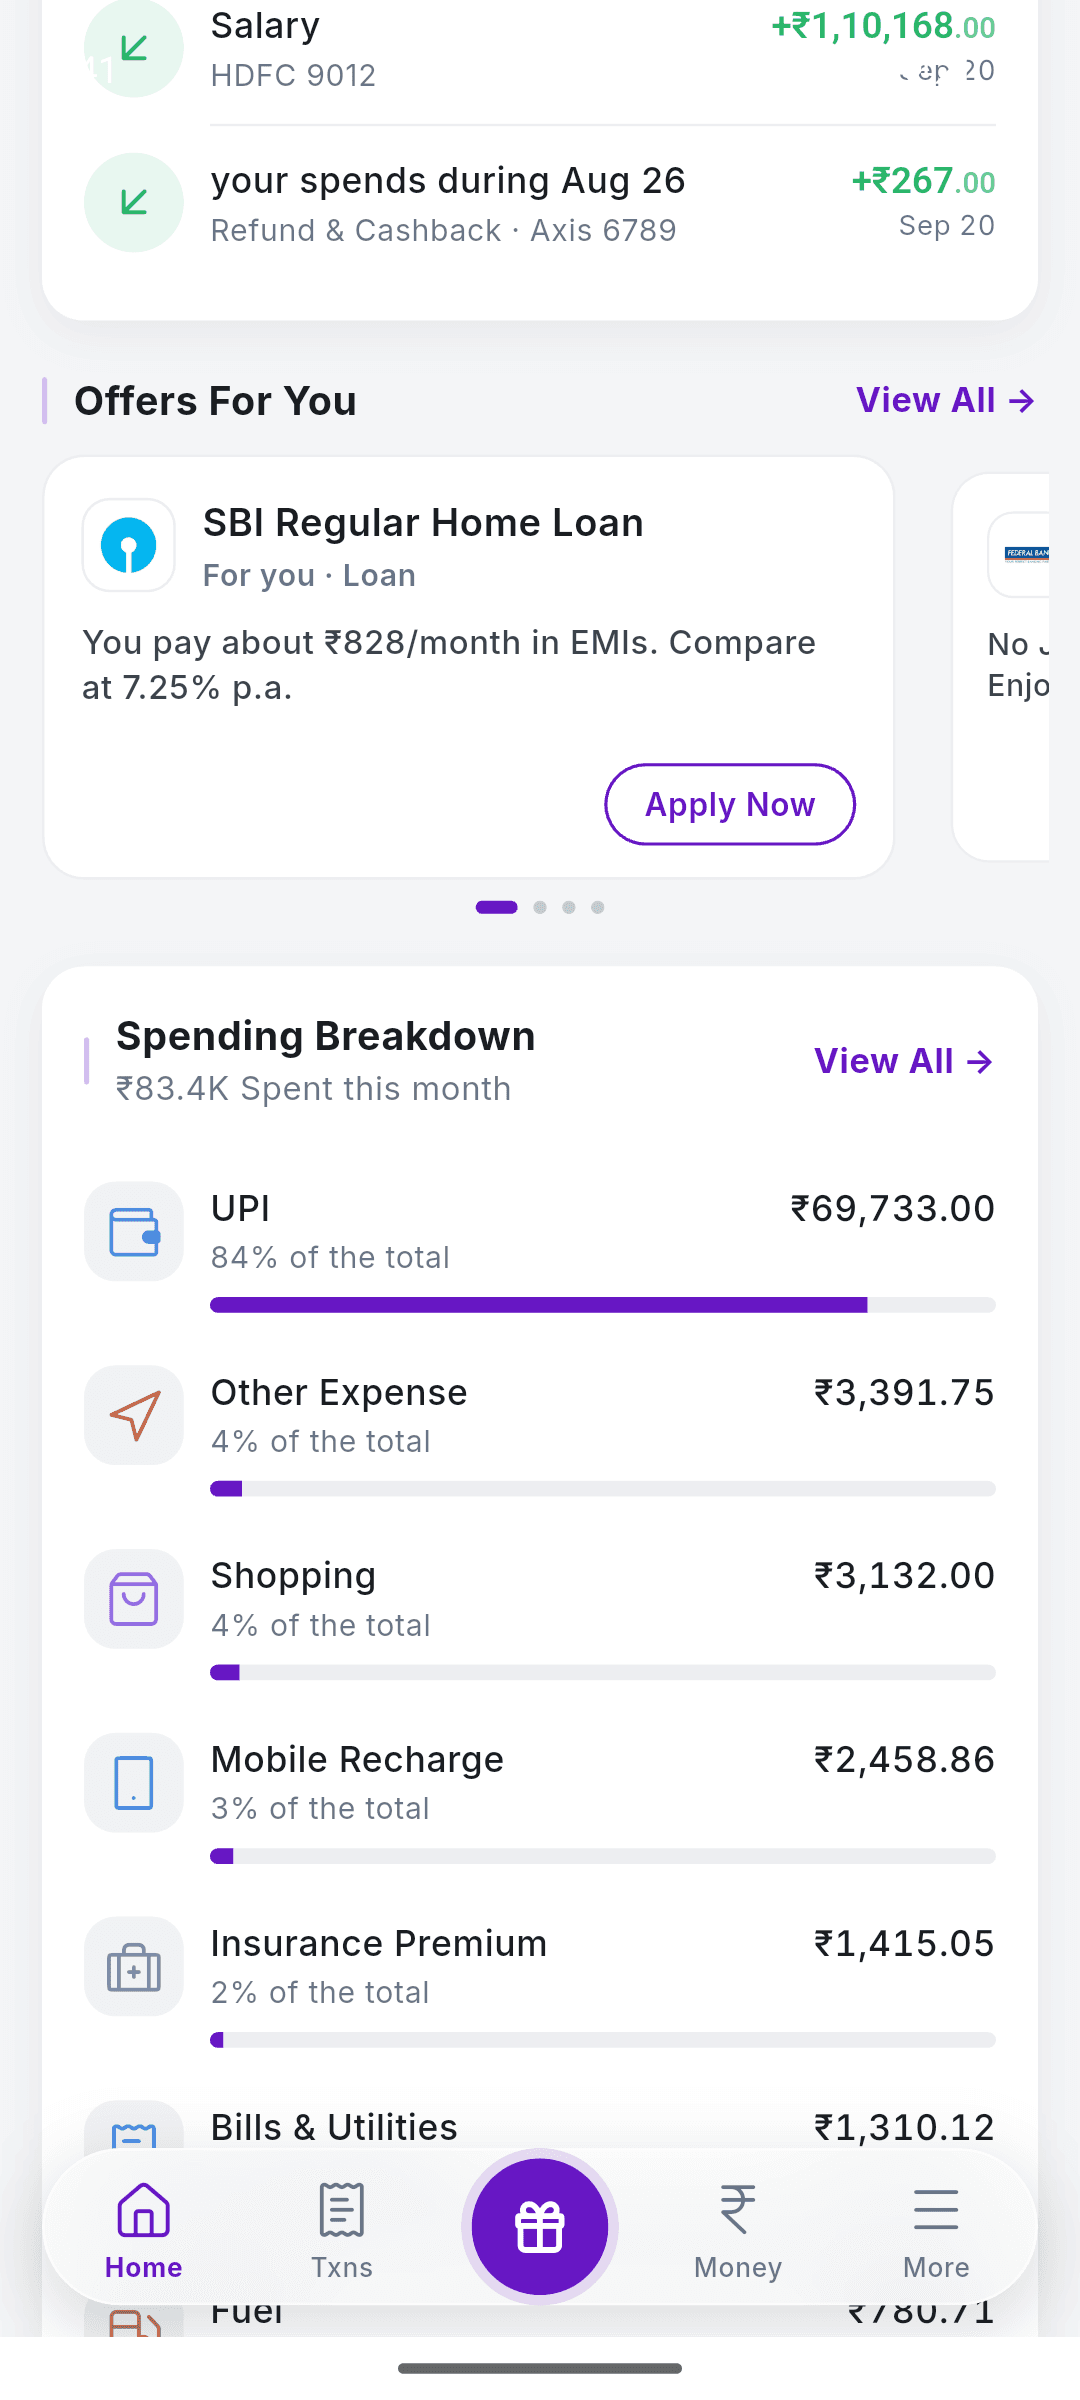
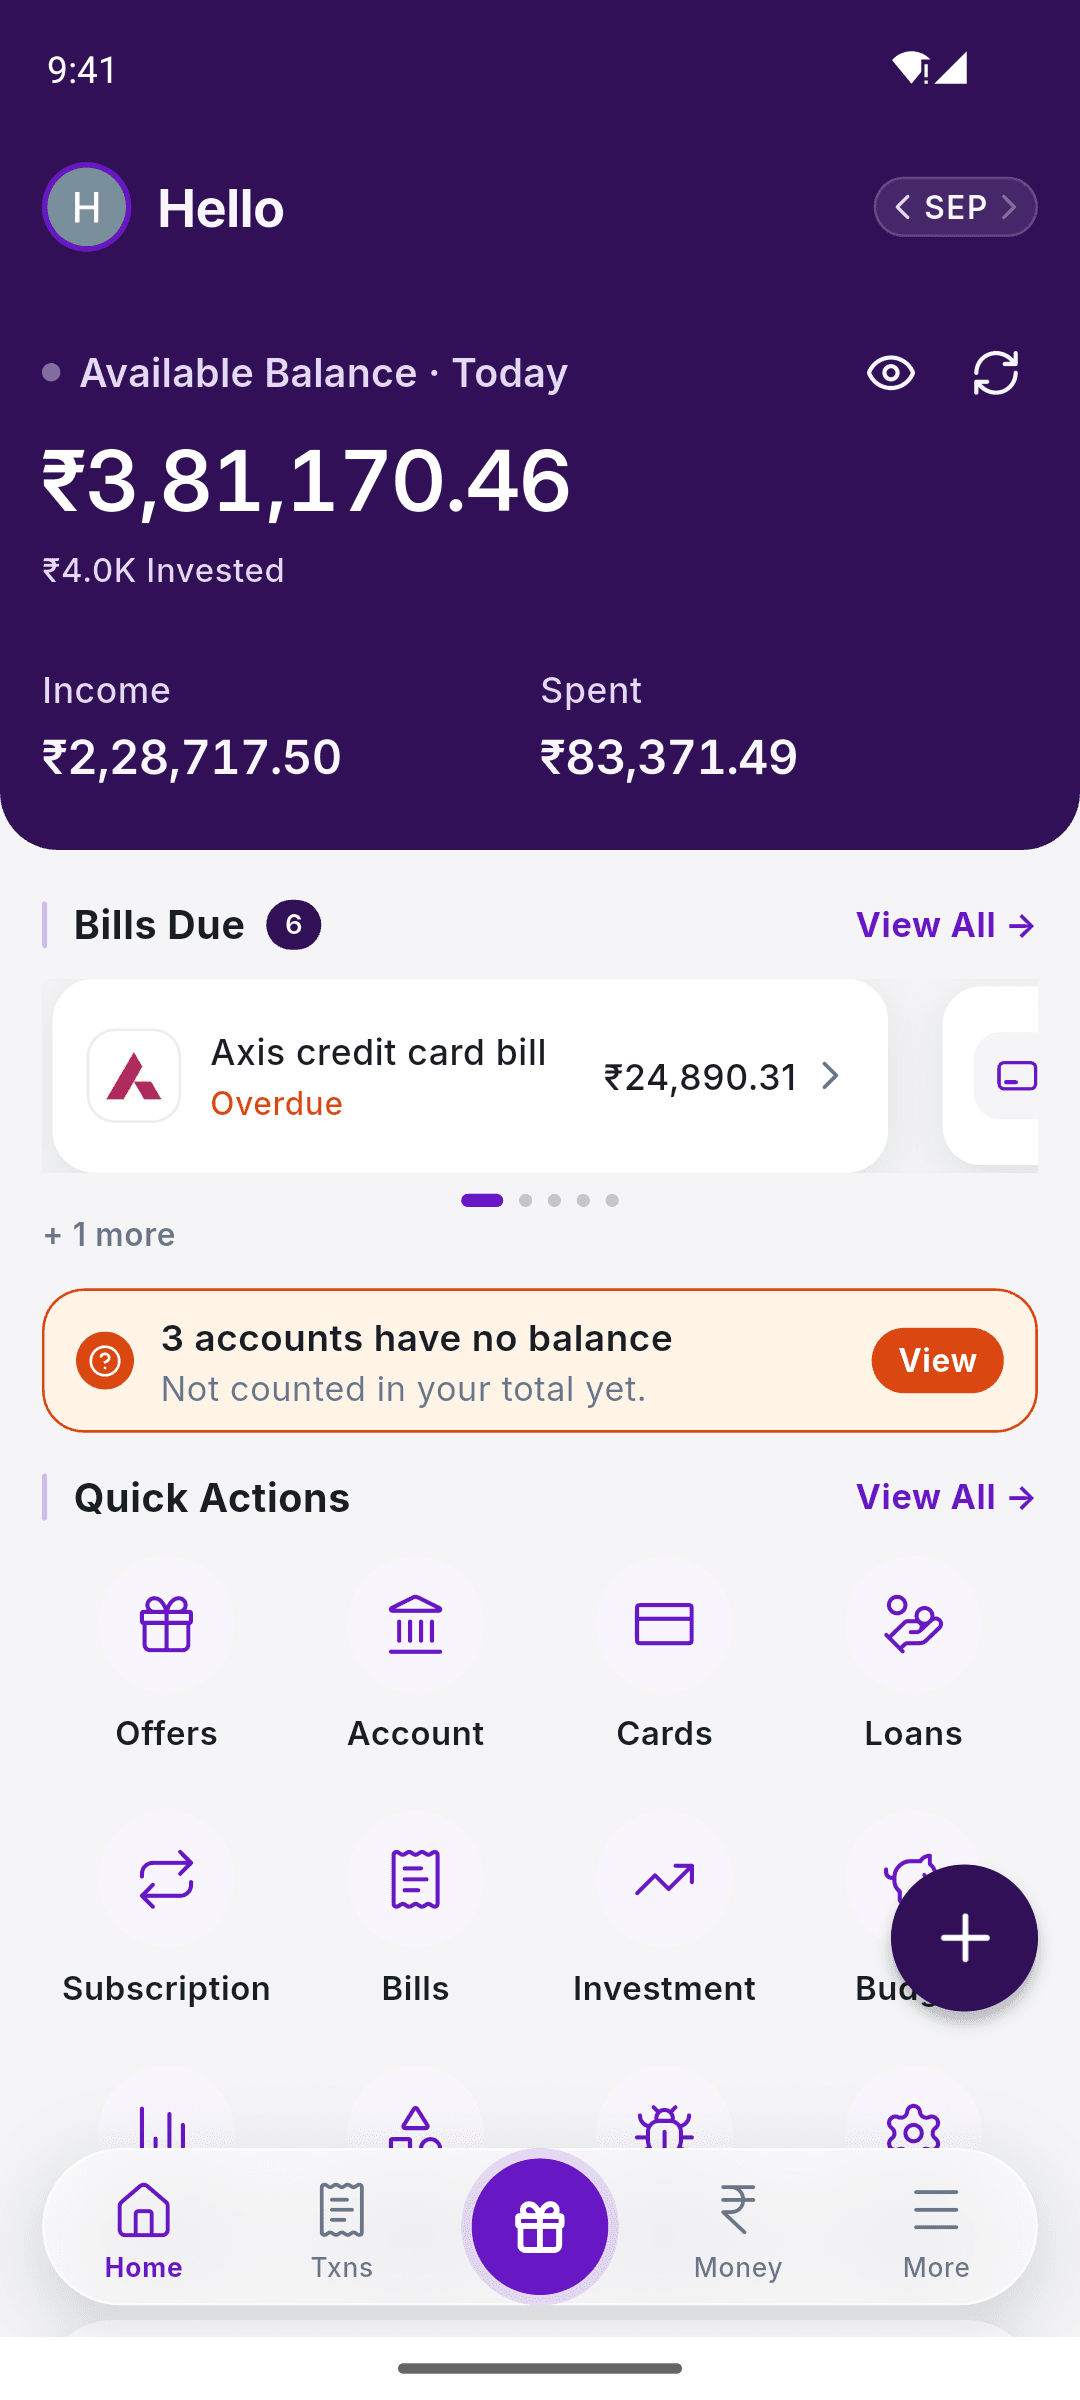
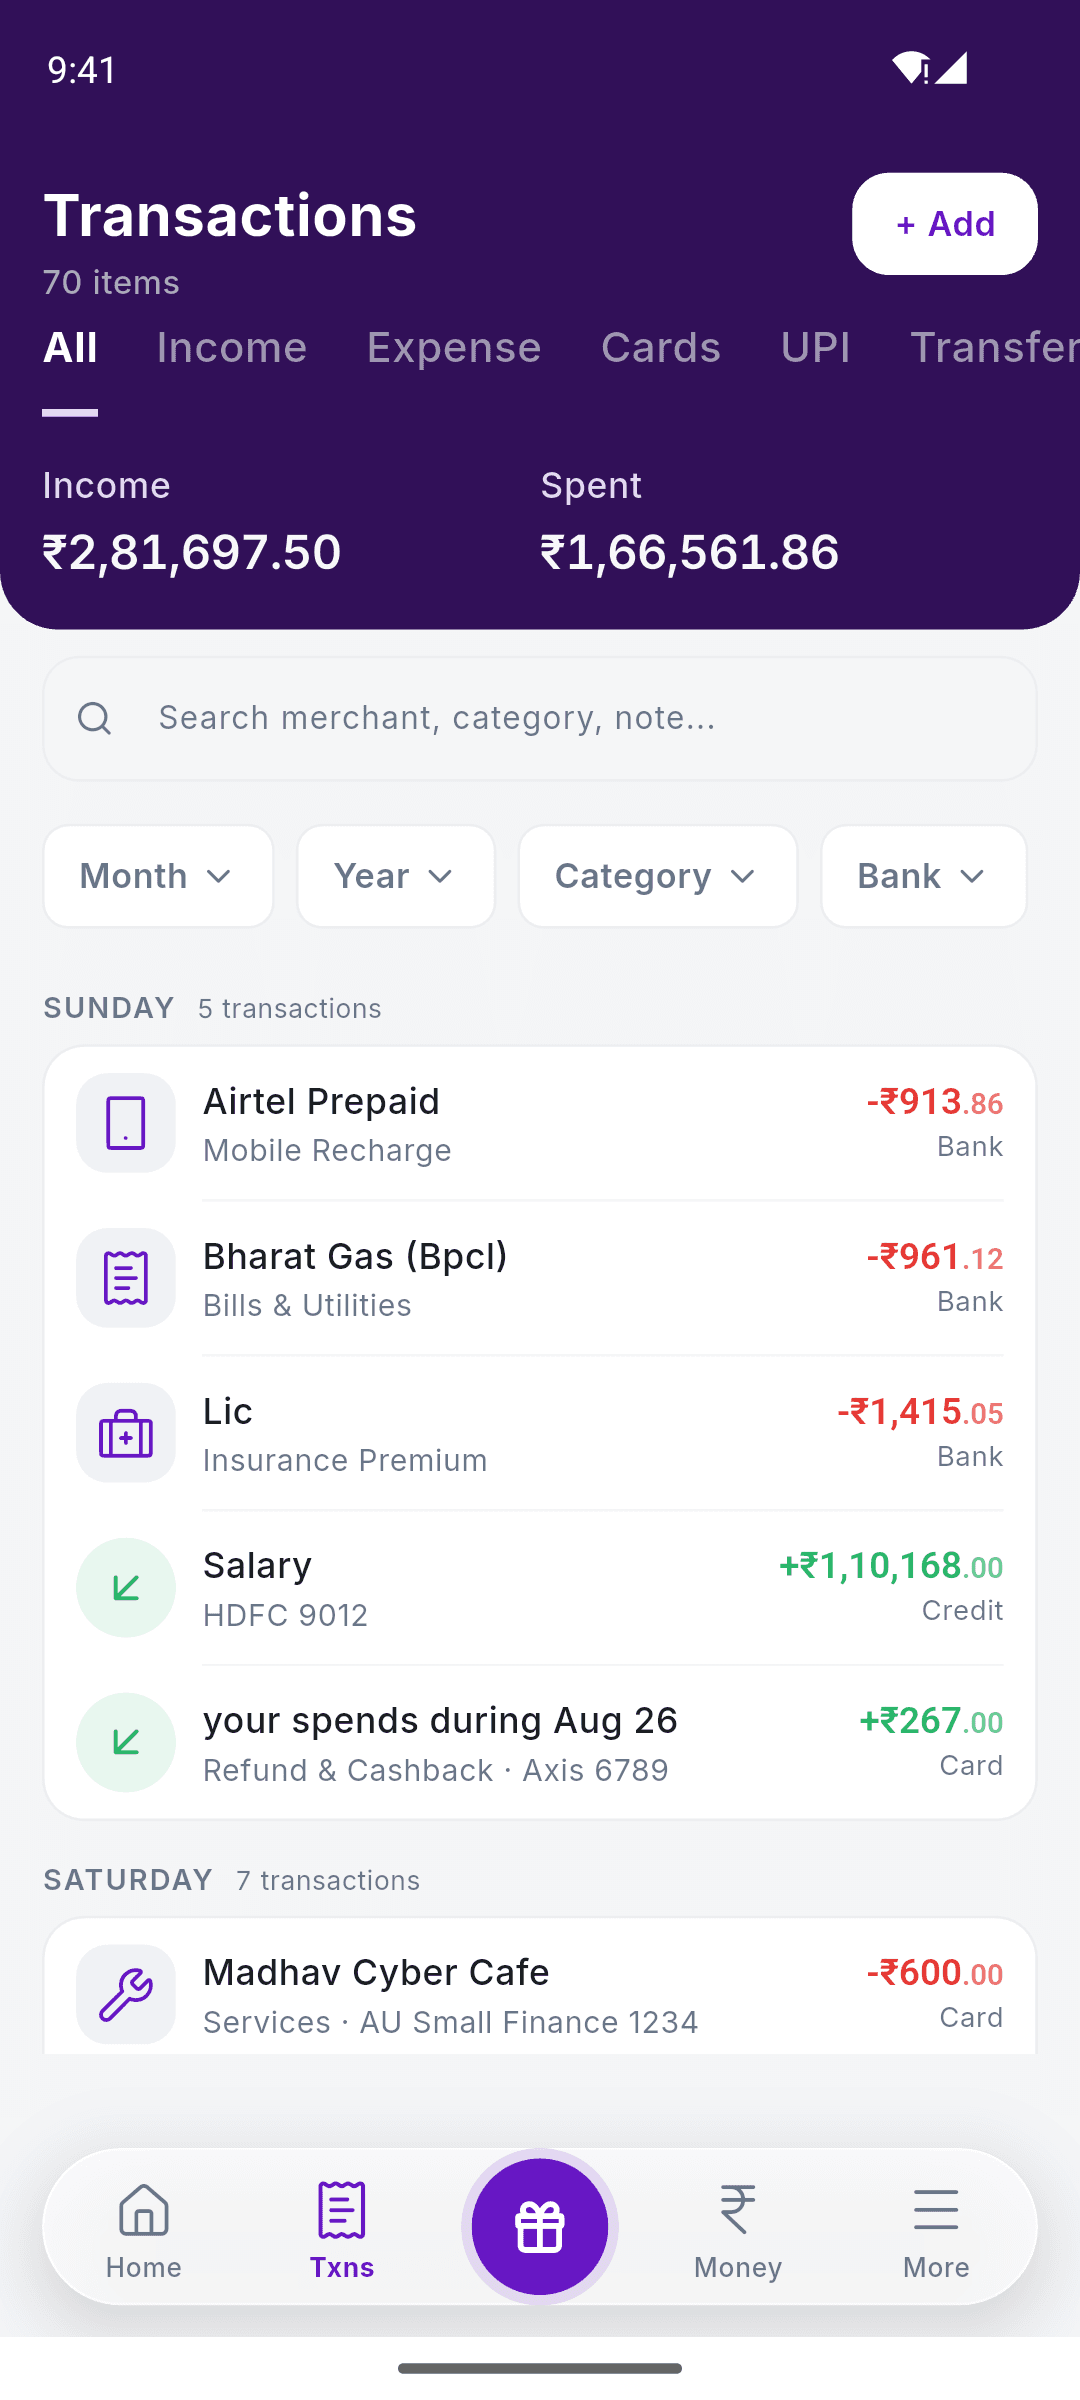
This is the truly hands-free option. An SMS-based expense tracker reads the transaction messages from your bank and card senders, pulls out the amount, date, account and shop, and adds each one to a list. You set it up once and then only open it to look.
Setting it up, step by step
- Install an SMS-based tracker on your Android phone. iPhones do not let apps read your SMS inbox, so this method is Android only.
- Allow SMS access when asked. A good app reads only messages from banks and card issuers and ignores personal chats and OTPs from friends.
- SkyloFin, for example, reads the last 90 days of bank SMS still on your phone on its first sync, so you see recent weeks straight away.
- Check the first week of categories. Fix any that are wrong (for example, a medical store tagged as Shopping). Good apps let you change the category.
- Add cash spends by hand as they happen, since cash never creates an SMS.
SkyloFin works this way. It reads bank and card SMS on your phone, turns each one into a transaction with amount, date, account or card, shop and category, and keeps the data on your phone rather than on its servers. There is no bank login and no net-banking password. If you want the details of how it reads messages, see how SkyloFin tracks your spending from SMS.

If you want to try it, SkyloFin is free on Android, with no ads and no bank login. You can turn SMS access off any time in your phone settings.
What it can and cannot do
It does not link to PhonePe, Google Pay or Paytm directly. It does not make payments or move money. It reads the bank SMS that each UPI payment triggers. SkyloFin is also a new app, so a few bank message formats are still being added. When it cannot read one, it can send the format with every number replaced by dummy values, never linked to you, so support for that bank can be added.
Method 2: The weekly ten-minute manual method
Maybe you use an iPhone, or you simply do not want any app reading your messages. You can still get almost the same result with a short weekly habit. Pick one fixed time, say Sunday evening.
- Open your SMS inbox and search for your bank’s sender name, or words like “debited” or “sent”.
- Scroll back to last Sunday. For each debit, note the date, amount and payee in a sheet or notebook.
- Add one word for the category: Food, Travel, Bills, Groceries, Shopping, Other.
- Skip self-transfers between your own accounts and money moved to a credit card bill (more on that below).
- Add any cash you spent that week from memory or from your wallet receipts.
- Total each category. Compare with last week.
If your bank’s SMS is patchy, use the bank app instead. Most bank apps let you download the account statement for a date range as a PDF or spreadsheet. A month’s statement covers every UPI debit, whichever app you paid from.
A sample week, sorted automatically vs by hand
Here is what one ordinary week looks like once the bank messages are sorted into categories.
| Day | Payment | Paid via | Amount | Category |
|---|---|---|---|---|
| Mon | Tea stall QR | PhonePe | ₹40 | Food |
| Tue | Swiggy order | Google Pay | ₹380 | Food |
| Wed | Petrol pump | Paytm | ₹1,200 | Travel |
| Thu | Electricity bill | Bank app | ₹1,650 | Bills |
| Fri | Grocery store | PhonePe | ₹920 | Groceries |
| Sat | Movie tickets | Google Pay | ₹600 | Entertainment |
| Sun | Vegetables | Cash | ₹250 | Groceries |
An SMS-based app builds the first six rows on its own. The Sunday cash row is the one you add yourself. Done by hand, the whole table takes about ten minutes a week. The real difference is not time, it is whether you keep doing it in month three.
The gaps: where UPI money slips past automatic tracking
Automatic does not mean perfect. Know these four gaps and you will not be surprised at month end.
1. Small UPI payments without an SMS
Some banks have stopped sending SMS for very small UPI payments to cut costs. HDFC Bank, for example, announced in 2024 that it would send UPI SMS alerts only for money sent above ₹100 and received above ₹500, with email alerts continuing for all UPI transactions. Check your own bank’s alert settings. If small debits come only by email, they will not reach an SMS reader, so a weekly look at the bank statement is a good safety net.
2. UPI Lite
UPI Lite is a small on-device balance for quick, PIN-free payments. Your bank sees the top-up when you load it, but the payments made from it are typically summed up in one SMS per day rather than one per payment. For tracking, treat the top-up as the spend and note the big items yourself, or keep UPI Lite for tiny daily spends only.
3. Self-transfers and card bill payments
Moving ₹10,000 from your salary account to your savings account is not spending. Neither is paying your credit card bill, because the card purchases were already counted when you made them. Mark these so they do not double your totals.
4. Cash
An ATM withdrawal shows up, but what you buy with that cash does not. Either log cash spends by hand or treat the whole withdrawal as one “Cash” expense.

Turning the list into something useful
A list of payments is only step one. The point is to answer two questions each month: where did the money go, and is that where I want it to go? Once your UPI spends are in categories, look at the top three. For most salaried people in cities, food delivery, shopping and travel are where the surprise sits.
Then set a monthly limit for the one category that surprised you most. SkyloFin’s budgets and savings goals warn you before you go over. On paper, simply write the limit at the top of the page and tick it down each Sunday. If you need a starting split for your salary, the 50-30-20 rule with Indian salary examples is a simple base.
Frequently asked questions
Can an app read my PhonePe or Google Pay history directly?
Not in the way people imagine. Most trackers, including SkyloFin, read the bank SMS that each UPI payment creates, not the UPI app itself. The result is similar, and it covers every UPI app at once.
Will automatic tracking work on an iPhone?
SMS-reading trackers need Android, because iOS does not let apps read your SMS inbox. On an iPhone, use the weekly manual method or your bank’s downloadable statement.
Is it safe to give an app SMS permission?
It depends on what the app reads and where the data goes. Look for an app that reads only bank senders and keeps data on the phone. Our guide on what expense tracker apps can see explains what to check.
Why is my monthly total lower than my bank statement?
Usually because of small UPI payments that came without an SMS, UPI Lite, or cash. Compare once with your bank statement and add what is missing.
Tracking UPI does not need willpower, it needs a system that runs without you. Try SkyloFin free on Android, or start the Sunday ten-minute habit tonight.
Last checked: October 2026.