
Your salary comes in on the 1st. Rent goes on the 5th. After that it is a blur of UPI payments, a card swipe at the mall, an OTT renewal and a few ATM visits. You know you spent “a lot”, but if someone asked for the exact figure, you would guess.
You can get the real number without any app. Your bank sends an SMS for almost every debit, so your inbox is already a record of the month. The method is: collect the debit messages, remove the ones that are not real spending, then add up the rest by category. It takes about 30 minutes the first time and less after that.
This guide walks through each step, with the rules for what to count, and a full worked example.
Step 1: Find all the debit messages
Open your SMS app and search, one at a time, for the words banks commonly use for money going out. Try your bank’s sender name first, then these words:
- “debited” for most UPI, IMPS and auto-debit messages
- “spent” or “used” for debit and credit card swipes
- “withdrawn” for ATM cash
- “sent” for some banks’ UPI messages
Banks word their messages differently, so open two or three of your own SMS to see which words your bank uses. Then scroll from the 1st to the last day of the month.
If you have more than one bank account or card, repeat for each. It is easier to work through one sender at a time than to mix them.
Step 2: Copy each debit into a simple list
A notebook works, but a sheet on your phone is quicker to total. Use four columns: Date, Amount, Paid to, Category. You do not need the reference number or balance.
Most debit SMS show the payee name or UPI ID, which is usually enough to pick a category. “VPA swiggy@…” is food. “BESCOM” or “MSEDCL” is electricity. If a payee is just a person’s name, decide whether it was your maid, your landlord or a friend you were paying back.
Tip: write the category the same way every time. “Food” in one row and “Eating out” in another will split one category into two when you add up.
Step 3: Remove what is not spending
This is the step most people get wrong, and it can inflate the total by tens of thousands. Not every debit SMS is an expense.

Transfers to your own accounts
Moving ₹15,000 from your salary account to your savings account, a fixed deposit or your spouse’s account for the household kitty is just money changing pockets. Leave it out, or the same rupee gets counted again when it is finally spent.
Credit card bill payment
If you count every card swipe as spending, and then also count the ₹18,000 bill payment, you count the same money twice. Pick one. The cleaner way is to count the swipes (you see what you bought) and skip the bill payment.
Refunds
A Myntra return or a cancelled train ticket shows up as a credit SMS. Subtract it from the category of the original purchase.
Investments and loan EMIs
Decide once and stay consistent. Many people keep SIPs and EMIs as a separate line called “Commitments”, outside day-to-day spending. That way you can see both the fixed part of your month and the part you control.
Step 4: Add up by category
Now total each category. Here is a worked example for Rahul, who earns ₹55,000 in hand in Bengaluru and has one salary account and one credit card.
| What the SMS showed | Amount | Count it? | Category |
|---|---|---|---|
| Rent by UPI to landlord | ₹16,000 | Yes | Housing |
| Transfer to own savings account | ₹10,000 | No | Transfer |
| SIP auto-debit | ₹5,000 | Separately | Commitments |
| Bike loan EMI | ₹3,200 | Separately | Commitments |
| Groceries (14 UPI payments) | ₹6,300 | Yes | Groceries |
| Swiggy and Zomato (11 payments) | ₹4,100 | Yes | Food delivery |
| Credit card swipes (mall, petrol, Amazon) | ₹9,400 | Yes | Shopping and travel |
| Credit card bill payment | ₹9,400 | No | Already counted |
| Electricity, mobile, broadband, OTT | ₹2,650 | Yes | Bills |
| ATM withdrawal | ₹3,000 | Yes | Cash |
| Refund from cancelled order | −₹1,200 | Yes | Shopping and travel |
Adding up only the rows marked Yes gives ₹40,250 of spending (₹16,000 + ₹6,300 + ₹4,100 + ₹9,400 + ₹2,650 + ₹3,000 − ₹1,200). Commitments are another ₹8,200. If Rahul had simply added every debit SMS, he would have got ₹69,050, which is more than his salary. That is why step 3 matters.
Step 5: Read the result, not just the total
A total alone does not change anything. Look at three things:
- Your biggest flexible category. For Rahul it is card spends at ₹8,200 after the refund, then groceries. Rent is large but fixed.
- Frequency. Eleven food orders at about ₹370 each feels small per order but adds to ₹4,100.
- Cash. ₹3,000 went out of the ATM and nobody knows where it went. Even a rough note helps.
If you want a simple target to compare against, the 50-30-20 rule with Indian salary examples is a good start.
When SMS alone is not enough
Bank SMS covers most of a month, but not all of it:
- Some banks no longer send SMS for very small UPI payments. HDFC Bank, for example, announced in 2024 that UPI SMS would go only for debits above ₹100, with email alerts for all UPI transactions.
- UPI Lite payments are usually reported in one daily summary SMS rather than one per payment.
- If you deleted old messages, they are gone from the inbox.
For a perfect figure, compare your SMS total with the bank statement once. If the difference is small, SMS is good enough from next month on.
The same thing, done for you
Doing this by hand once is useful. It shows you exactly how your money moves. Doing it every month is where most people stop.
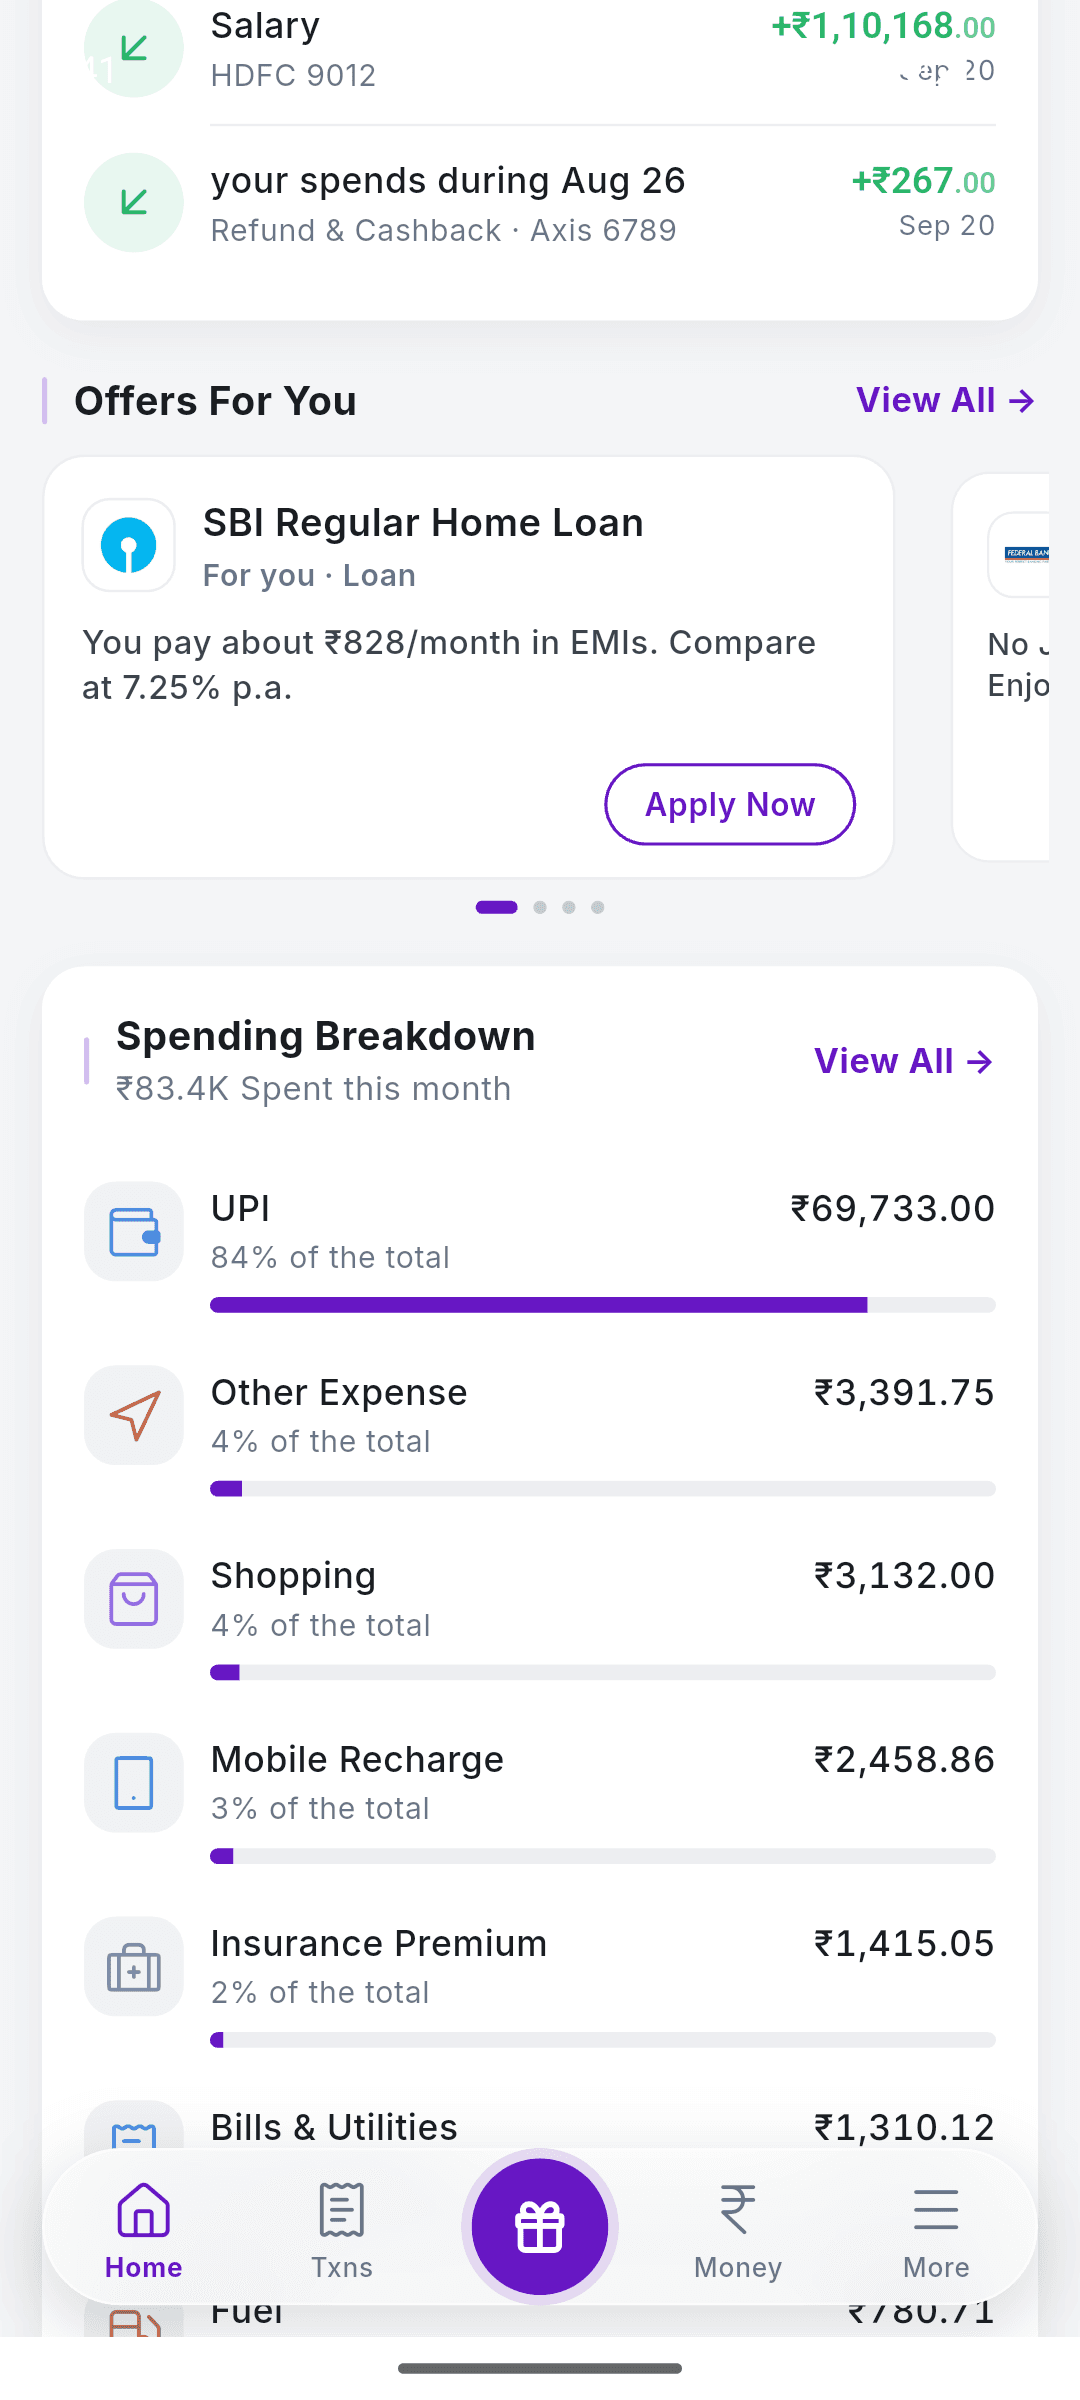
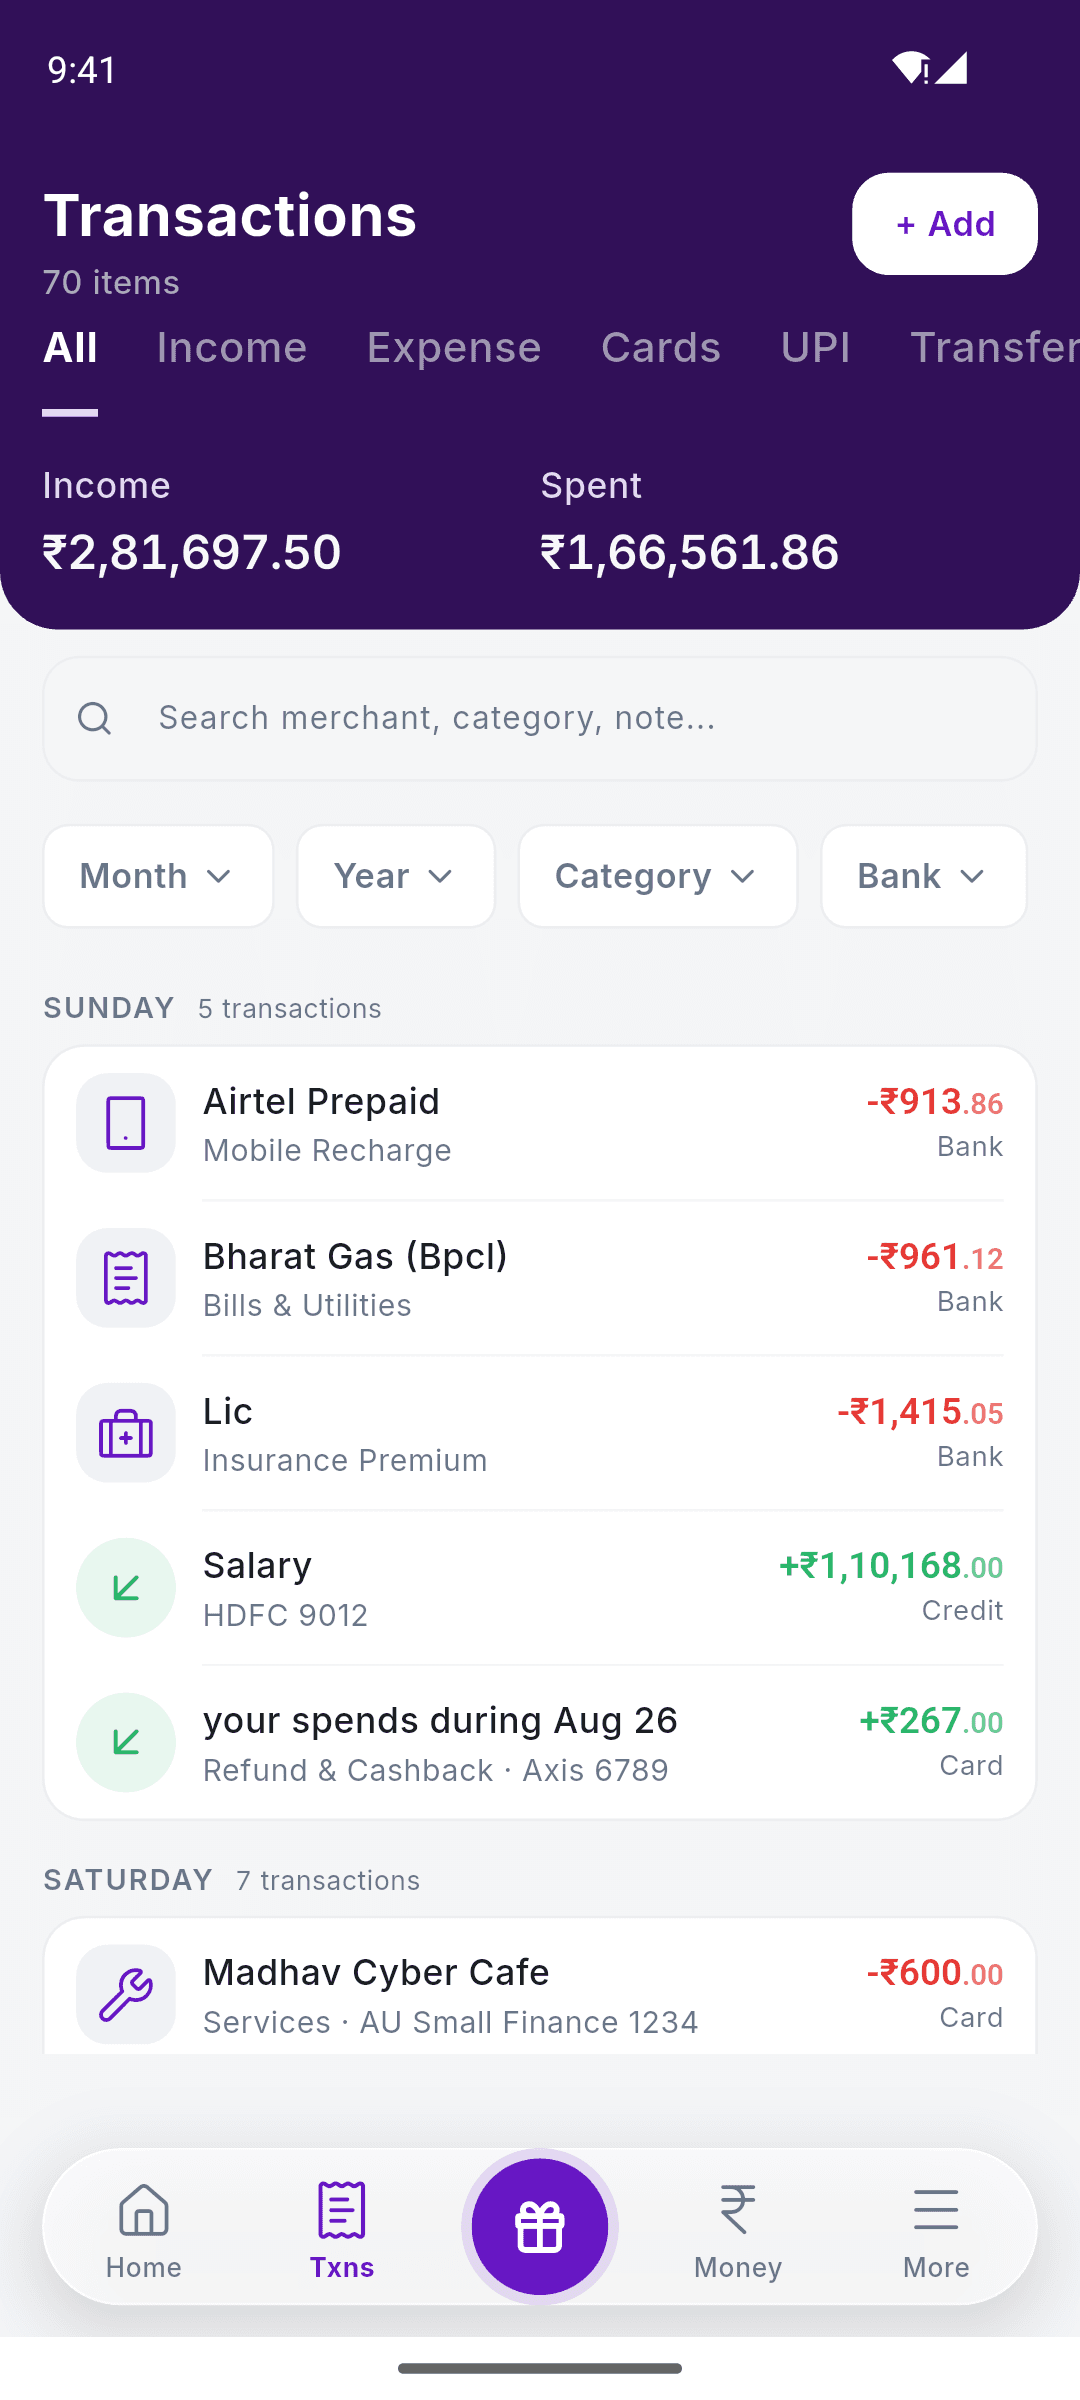
An SMS-based tracker does steps 1, 2 and 4 on its own. SkyloFin reads your bank and card SMS on the phone, turns each into a transaction with amount, date, account, shop and category, and shows spending by category month by month. You can change any category, and you still choose what counts. SkyloFin is free on Android, with no ads and no bank login. Data stays on your phone.

If you are curious how the reading works, see how transactions work in the app guide and how categories work.
Frequently asked questions
Should I count credit card swipes or the credit card bill?
Count one, not both. Counting swipes is better, because you see what you bought and in which month.
Is a transfer to my parents spending?
If the money supports them, yes, count it as Family. If it is your own money parked in their account, it is a transfer.
My SMS total is lower than my statement. Why?
Usually small UPI payments sent without SMS, UPI Lite, or deleted messages. The statement is the full record.
I have three bank accounts. Do I need all of them?
Only the accounts you spend from. If one account only holds savings or an FD, skip it, but do count any money that leaves it for a purchase. Most people find that one or two accounts carry almost all of their spending.
How often should I do this?
Monthly is enough to see the pattern. Weekly is better if you want to change it before the month ends.
Your inbox already has the answer to where your salary went. Spend 30 minutes with it this weekend, or let SkyloFin add it up for you.
Last checked: October 2026.
Updated 13 Oct 2026.