
Tracking your spending by hand is slow, so most people now use an app that does it for them. That is sensible. But an expense tracker sees more about you than almost any other app on your phone: what you earn, what you owe, where you shop and how often. Before you give one that access, it is worth knowing how it gets your data and where that data goes.
There are three main ways these apps work. None is automatically good or bad. Each one is a trade between convenience and how much of your financial life leaves your phone.
Type 1: you enter everything yourself
The simplest kind. You type each expense, the app adds them up.
- What it can see: only what you type.
- Where the data goes: depends on the app. Some keep it on the phone, some sync it to their servers so you can use it on more than one device.
- The catch: it is only as good as your typing. Most people stop within a few weeks.
Type 2: the app reads your bank SMS
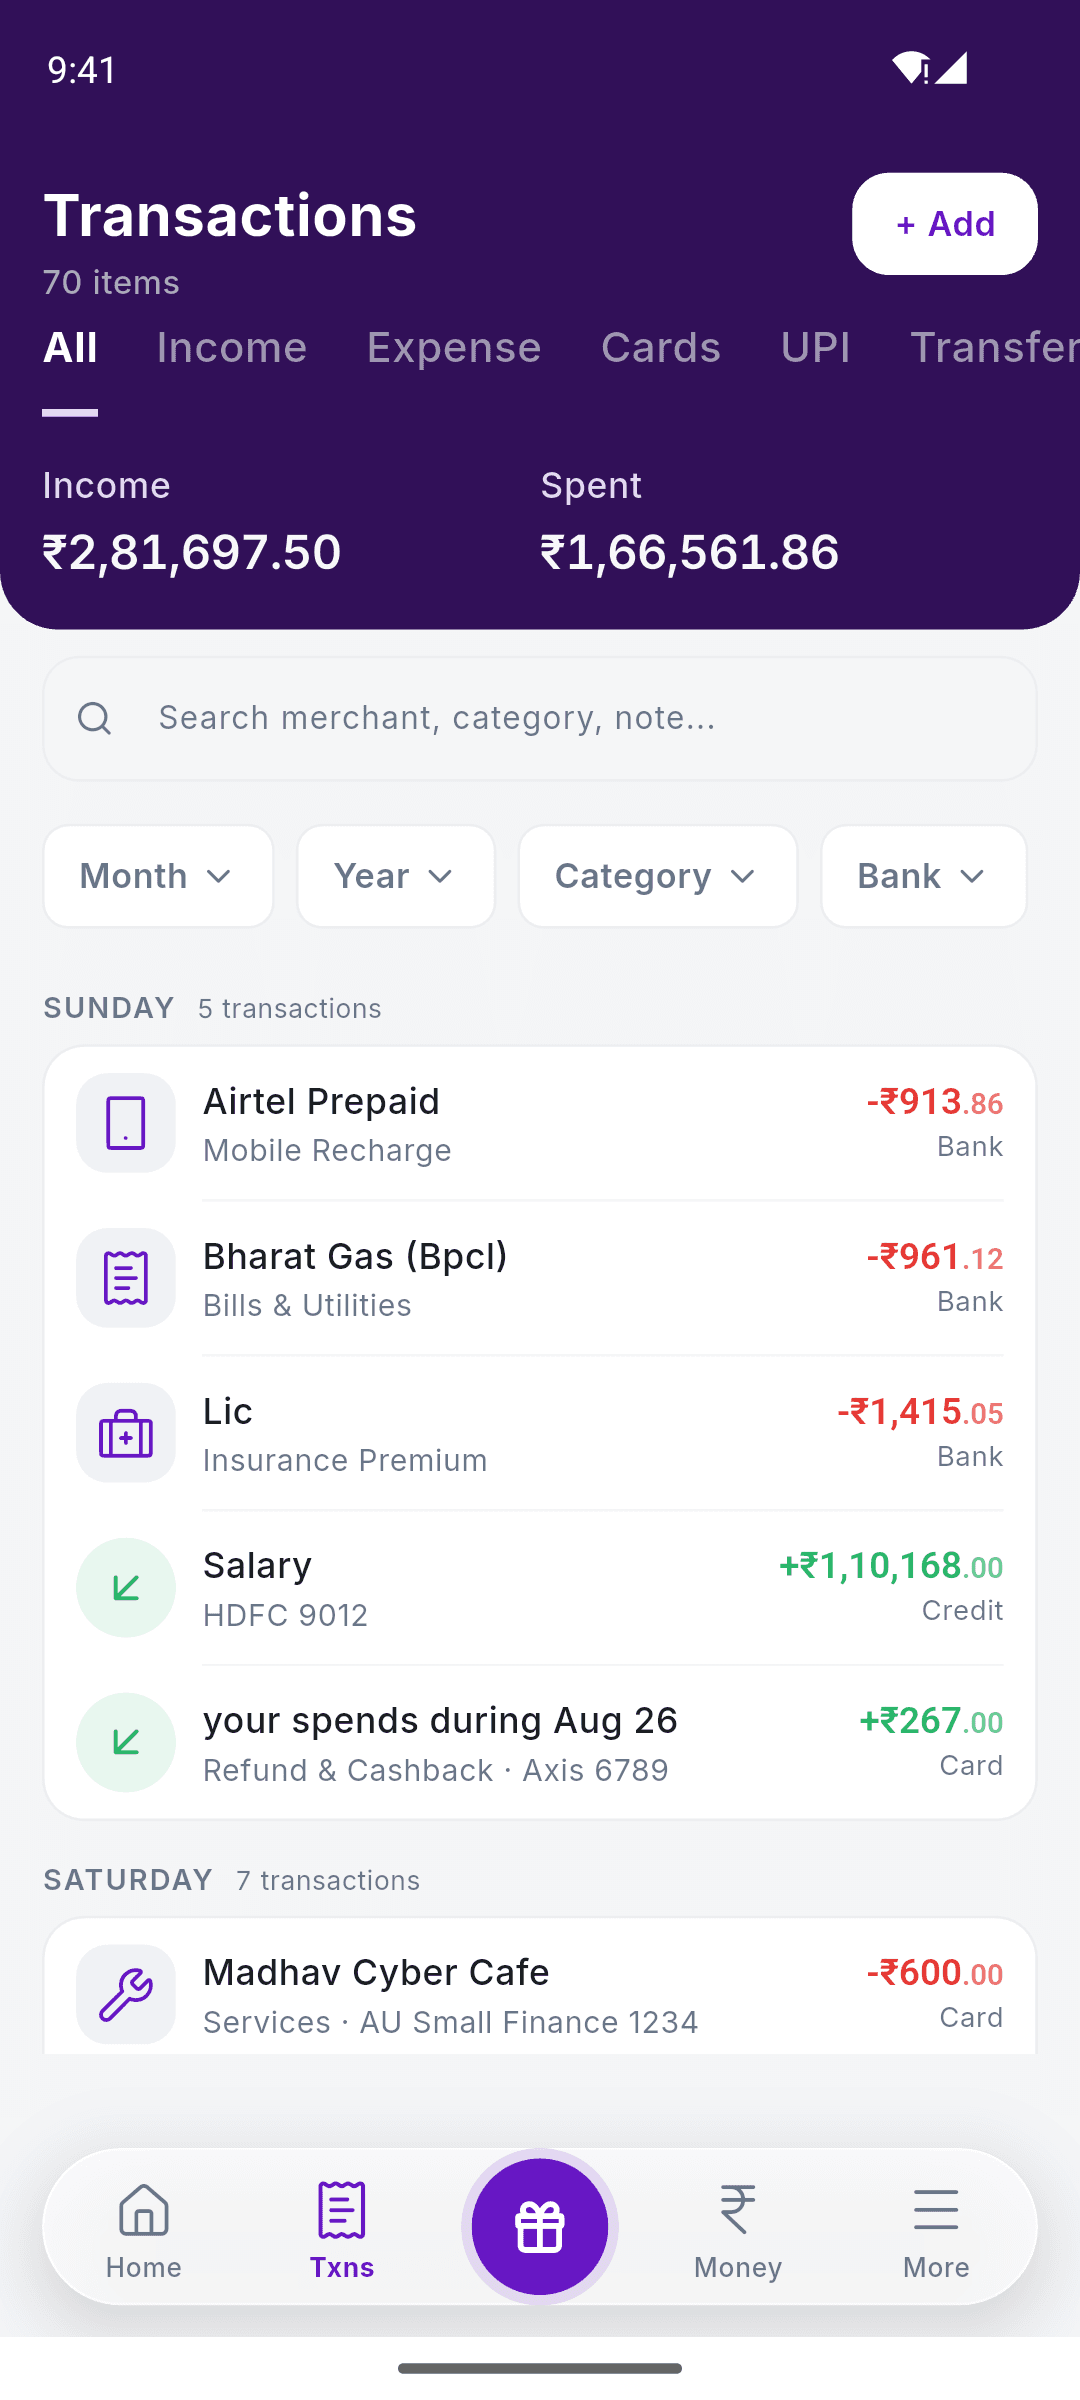
Your bank already sends you an SMS for every UPI payment, card swipe and ATM withdrawal. An SMS-based tracker asks for permission to read your messages and turns those alerts into transactions automatically.
- What it can see: the app technically gets access to your SMS inbox. A well-built app only picks out messages from banks and card companies and ignores the rest.
- Where the data goes: this is the question that matters. Some apps read the messages on your phone and keep the results there. Others upload your messages or transactions to their servers to process them.
- The catch: SMS formats differ from bank to bank, so an app can sometimes miss or misread a transaction.
On Android, reading SMS is a restricted permission. Google Play only lets an app use it for a core purpose it has declared, and apps have to fill in a Data safety section on their store listing saying what they collect and share. That section is worth reading before you install.
Type 3: the app links to your bank account
In India, the regulated way for an app to fetch your bank data is the Account Aggregator framework set up by the Reserve Bank of India. You pick an Account Aggregator, give consent in its app, and your bank sends your statements to the finance app you chose.
- What it can see: exactly what your consent covers: which accounts, what kind of data, for how long, and for what purpose. Consent can be revoked.
- Where the data goes: the Account Aggregator passes the data along without being able to read it; the finance app receives it on its side.
- The catch: your statements now sit with the app that received them, and you rely on its own policies for how long it keeps them and what it does with them.
Be careful with any app that asks for your net banking password or card PIN. No legitimate expense tracker needs them, and your bank tells you never to share them.
Side by side
| Manual entry | Reads bank SMS | Linked via Account Aggregator | |
|---|---|---|---|
| Effort | High | Low | Low |
| What it gets | What you type | Bank and card alerts | Statements you consent to |
| Can it stay on your phone? | Yes, if the app is built that way | Yes, if the app is built that way | No, the data is sent to the app |
| Needs a bank login? | No | No | No, consent is given in the Account Aggregator’s app |
Six questions to ask any money app
- Where is my data stored? On my phone, or on your servers? Look for a plain answer in the privacy policy, not “may be processed”.
- What is sent to your servers, exactly? Even phone-first apps send something: an account, crash reports, analytics. Ask what.
- Who else gets it? Check the Data safety section on Google Play for “data shared with third parties”.
- What permissions does it ask for, and why? A tracker needs to read SMS. It has no reason to send SMS, read your contacts or know your location.
- Can I delete everything? On the phone, in the backup, and my account on your servers.
- Who runs it? A company name, an address and a support contact you can actually reach.
How SkyloFin answers those questions
We built the SkyloFin app as an SMS-based tracker that keeps your money data on your phone. Here are our own answers, including the parts that are not “zero”:
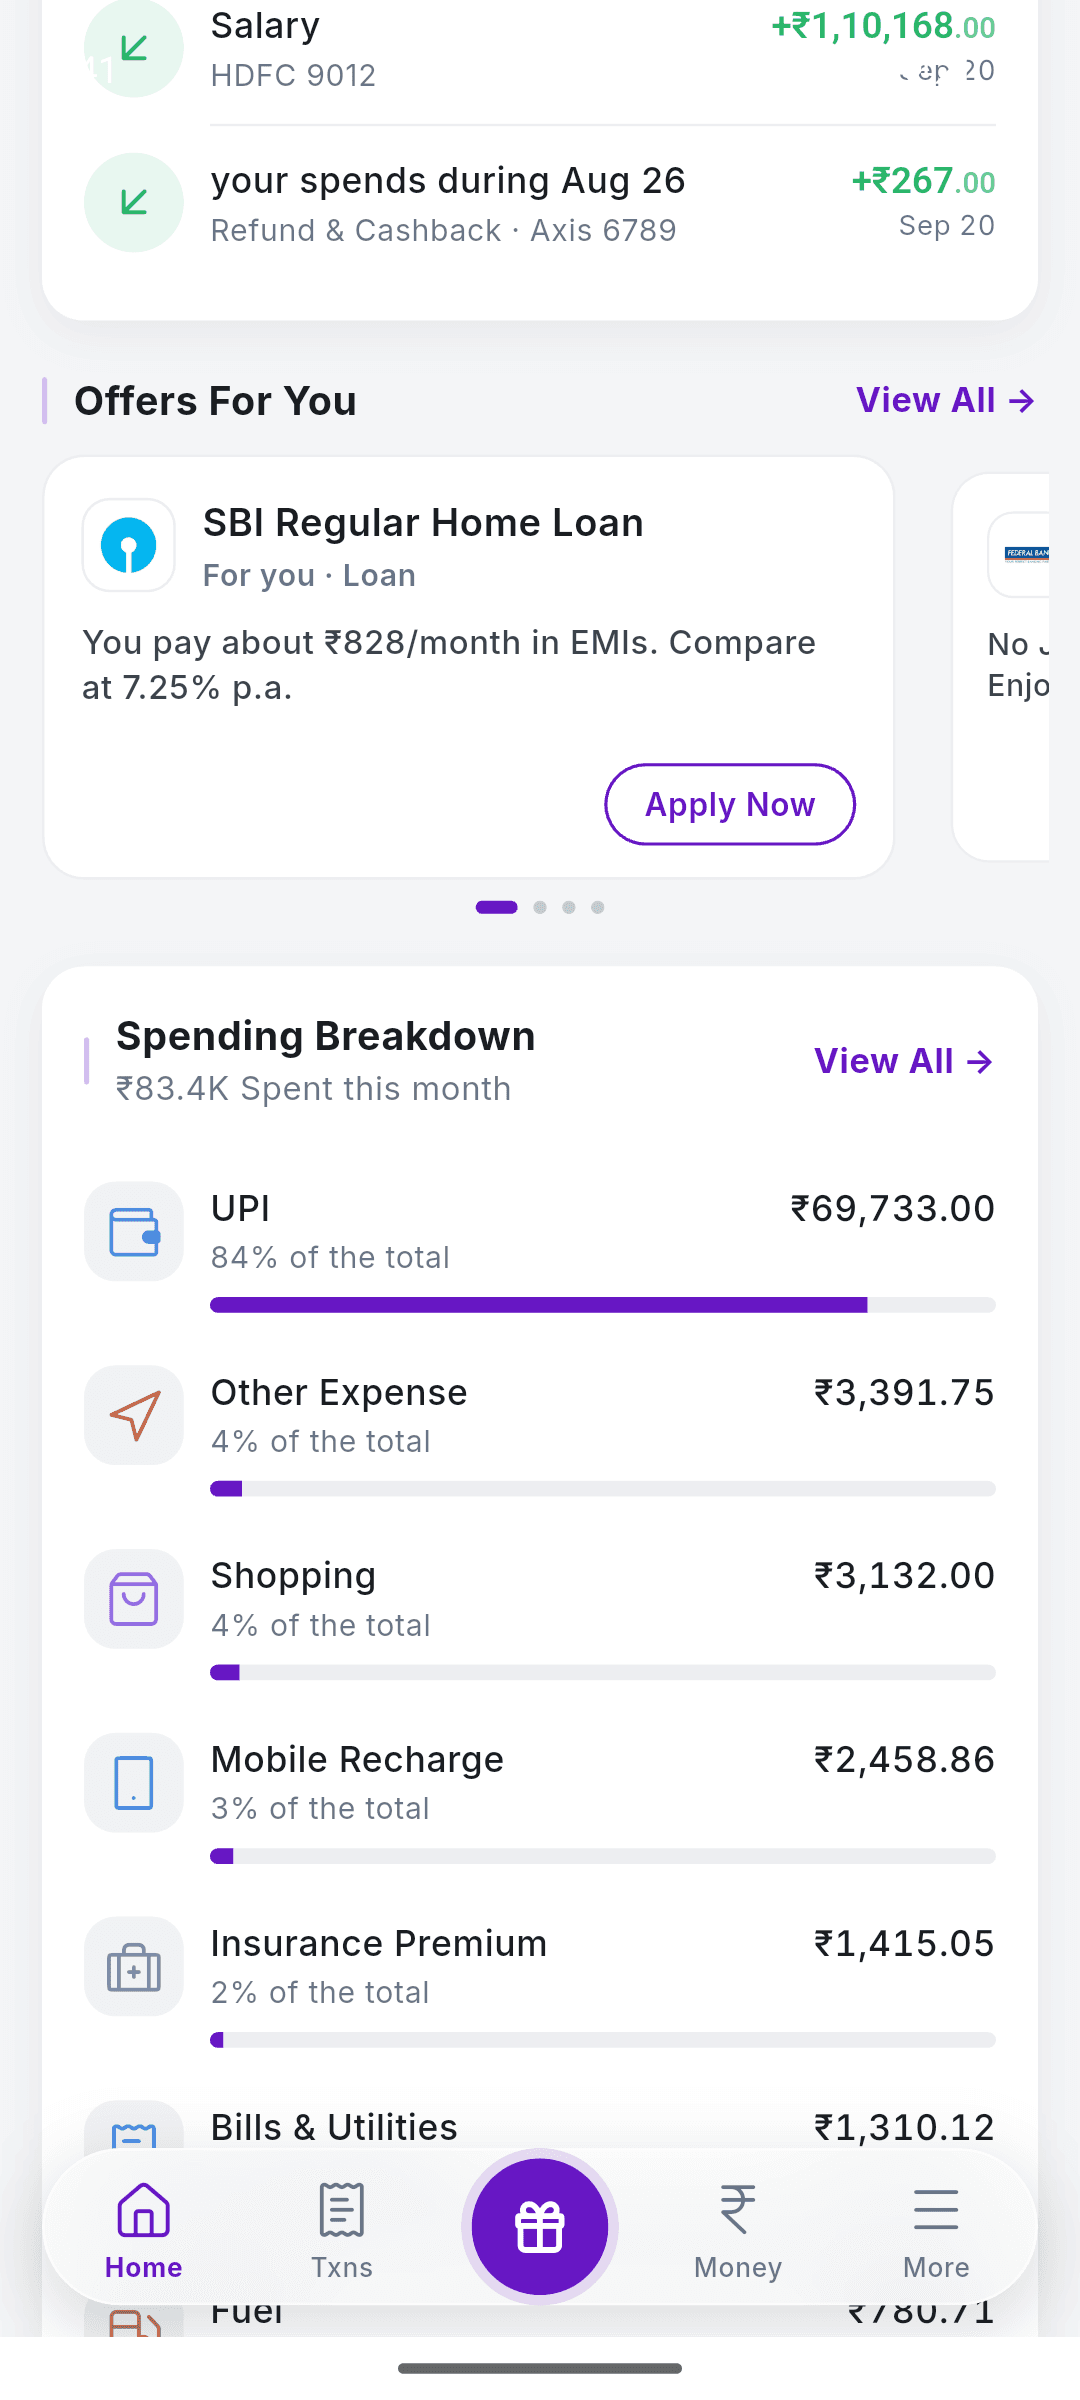
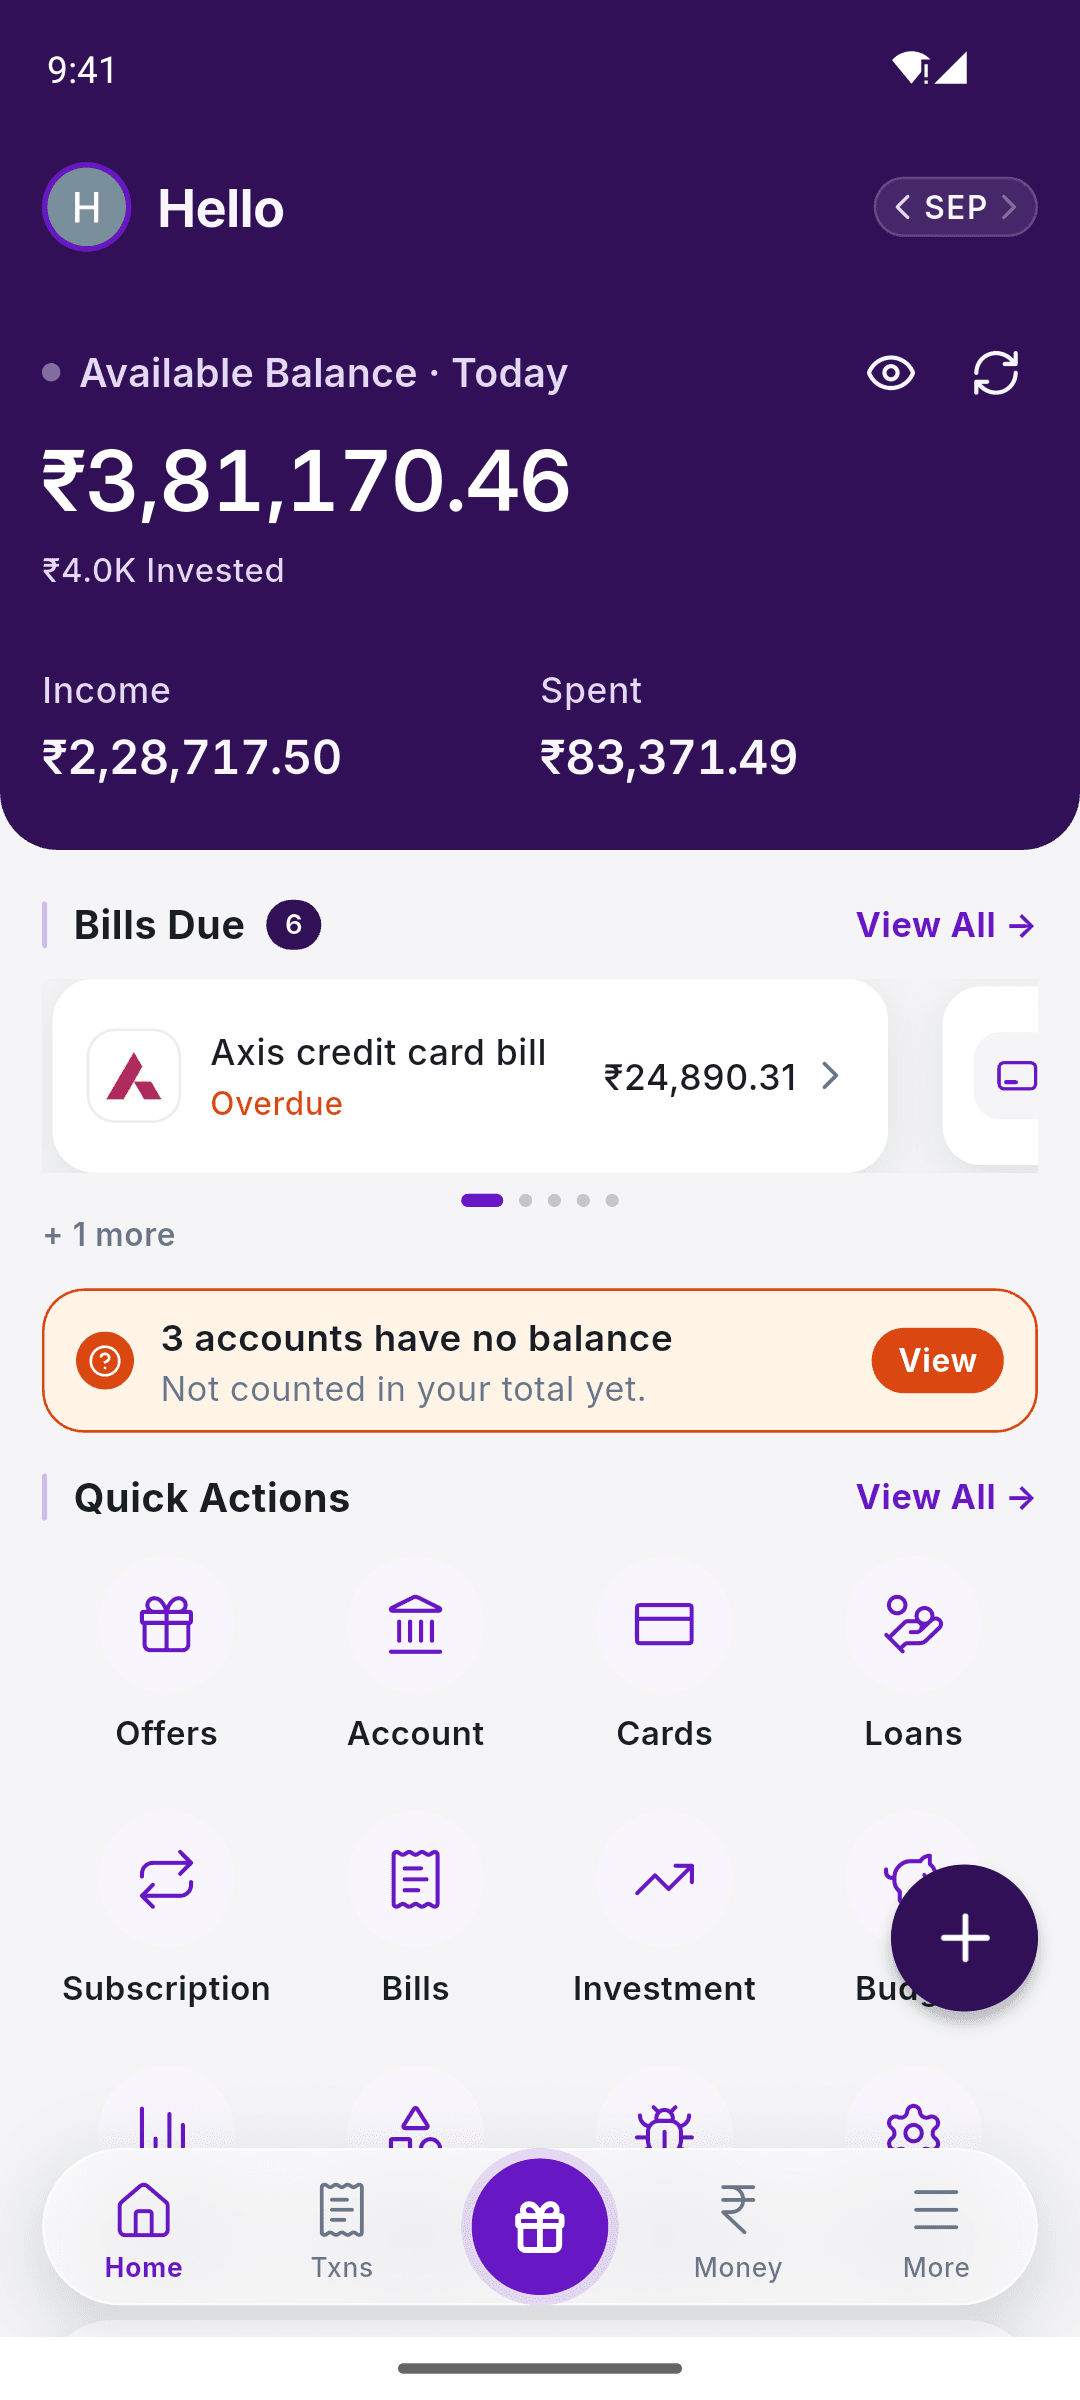
- Your transactions stay on your phone. The app reads bank alerts on the device and stores the results there. Your spending data is not on our servers.
- Backups go to your own Google Drive, encrypted, in a folder only the app can open, so you can restore on a new phone.
- One exception, stated plainly: when the app finds a bank message format it cannot read yet, it may send us that format as a template with every real number, amount and account replaced, so we can learn to read it. It is not linked to you.
- We do keep an account record: your name, email and optional phone number, on servers in India, so you can sign in.
- It only reads SMS. It cannot send or delete messages, and it never asks for a bank login.
- You can delete everything from inside the app: local data, the Drive backup and your account.
The full details are on Is SkyloFin safe? and in our privacy policy.
The short version
Convenience and privacy do not have to be opposites. Before you install any money app, read three things: its privacy policy, its Data safety section on Google Play, and the permissions it asks for. If an app cannot tell you in one sentence where your transactions are stored, that is your answer.
Frequently asked questions
Is it safe to give an app SMS permission?
It can be, if the app only reads bank messages, keeps what it reads on your phone, and says so clearly. Check its Data safety section and privacy policy first.
Is the Account Aggregator framework safe?
It is regulated by the Reserve Bank of India and built on consent: you choose what to share, with whom and for how long, and you can revoke it. Your data still ends up with the app you shared it with.
Should any app ask for my net banking password?
No. Never share your net banking password, card PIN or OTP with an expense tracker.
Can SkyloFin see my spending?
No. Your transactions stay on your phone and in your own Google Drive backup. The only thing that can reach us from your messages is an anonymised template of a format the app cannot read yet.
This is general information, not legal or financial advice. How any app handles your data is set out in its own privacy policy and Google Play Data safety section.
Updated 3 Oct 2026.